Finance Research Group Working Papers,
University of Aarhus, Aarhus School of Business, Department of Business Studies
Downloads from S-WoBA
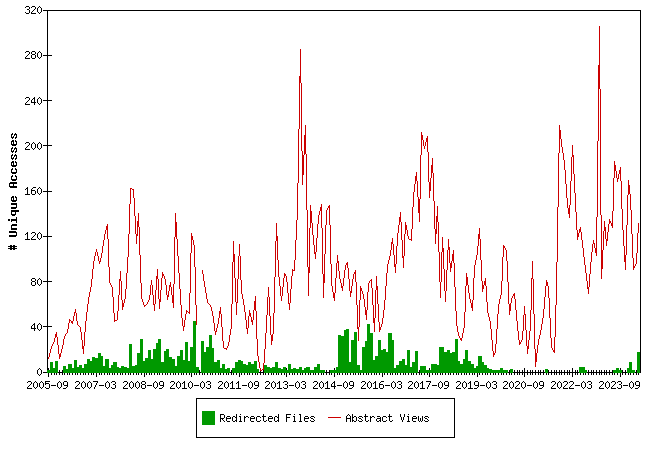
Fulltext files are files downloaded from the S-WoBA server, Redirected files are files downloaded from a server maintained by the publisher of a working paper series.
The statistics for 2010-06, 2012-04 (half month), 2012-05 and 2012-06 have unfortunately been lost. We regret this.
The raw data
Papers at S-WoBA
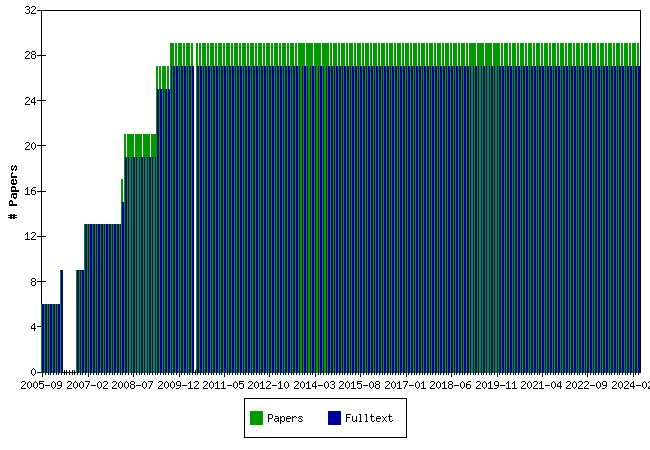
The raw data
Top papers by Abstract Accesses last month (2026-09)
| Paper | Accesses |
Traffic Light Options
Peter Løchte | 30 |
Estimating US Monetary Policy Shocks Using a Factor-Augmented Vector Autoregression: An EM Algorithm Approach
Lasse Bork | 30 |
The Fractional Ornstein-Uhlenbeck Process: Term Structure Theory and Application
Espen P. Høg, Per H. Frederiksen | 28 |
Time Charters with Purchase Options in Shipping: Valuation and Risk Management
Peter Løchte Jørgensen, Domenico De Giovanni | 28 |
Conducting event studies on a small stock exchange
Jan Bartholdy, Dennis Olson, Paula Peare | 27 |
Sato Processes in Default Modeling
Thomas Kokholm, Elisa Nicolato | 25 |
A Consistent Pricing Model for Index Options and Volatility Derivatives
Rama Cont, Thomas Kokholm | 23 |
Investment Timing, Liquidity, and Agency Costs of Debt
Stefan Hirth, Marliese Uhrig-Homburg | 22 |
Dispersed Trading and the Prevention of Market Failure: The Case of the Copenhagen Stock Exchange
David C. Porter, Carsten Tanggaard, Daniel G. Weaver, Wei Yu | 21 |
Lapse Rate Modeling: A Rational Expectation Approach
Domenico De Giovanni | 21 |
Danish Mutual Fund Performance - Selectivity, Market Timing and Persistence.
Michael Christensen | 21 |
Level-ARCH Short Rate Models with Regime Switching: Bivariate Modeling of US and European Short Rates.
Charlotte Christiansen | 21 |
Rank papers for other periods
Top papers by Downloads last month (2026-09)
| Paper | Downloads |
Habit persistence: Explaining cross-sectional variation in returns and time-varying expected returns
Stig Vinther Møller | 5 |
Sato Processes in Default Modeling
Thomas Kokholm, Elisa Nicolato | 4 |
Estimating US Monetary Policy Shocks Using a Factor-Augmented Vector Autoregression: An EM Algorithm Approach
Lasse Bork | 4 |
On the Generalized Brownian Motion and its Applications in Finance
Esben Høg, Per Frederiksen, Daniel Schiemert | 4 |
Investment decisions with benefits of control
Thomas Poulsen | 4 |
Debt and Taxes: Evidence from bank-financed unlisted firms
Jan Bartholdy, Cesário Mateus | 3 |
Time Charters with Purchase Options in Shipping: Valuation and Risk Management
Peter Løchte Jørgensen, Domenico De Giovanni | 3 |
The Fractional Ornstein-Uhlenbeck Process: Term Structure Theory and Application
Espen P. Høg, Per H. Frederiksen | 3 |
Lognormal Approximation of Complex Path-dependent Pension Scheme Payoffs
Peter Løchte Jørgensen | 3 |
Danish Mutual Fund Performance - Selectivity, Market Timing and Persistence.
Michael Christensen | 3 |
Investment Timing, Liquidity, and Agency Costs of Debt
Stefan Hirth, Marliese Uhrig-Homburg | 3 |
A Consistent Pricing Model for Index Options and Volatility Derivatives
Rama Cont, Thomas Kokholm | 3 |
Pricing of Traffic Light Options and other Correlation Derivatives
Thomas Kokholm | 3 |
Volatility and realized quadratic variation of differenced returns : A wavelet method approach
Esben Høg | 3 |
Decomposing European bond and equity volatility
Charlotte Christiansen | 3 |
Pricing the Option to Surrender in Incomplete Markets
Andrea Consiglio, Domenico De Giovanni | 3 |
Traffic Light Options
Peter Løchte | 3 |
Rank papers for other periods
Top papers by Abstract Accesses last 3 months (2026-07 to 2026-09)
| Paper | Accesses |
Improving the asset pricing ability of the Consumption-Capital Asset Pricing Model?
Anne-Sofie Reng Rasmussen | 91 |
The Fractional Ornstein-Uhlenbeck Process: Term Structure Theory and Application
Espen P. Høg, Per H. Frederiksen | 88 |
Estimating US Monetary Policy Shocks Using a Factor-Augmented Vector Autoregression: An EM Algorithm Approach
Lasse Bork | 83 |
Traffic Light Options
Peter Løchte | 81 |
A Consistent Pricing Model for Index Options and Volatility Derivatives
Rama Cont, Thomas Kokholm | 77 |
Conducting event studies on a small stock exchange
Jan Bartholdy, Dennis Olson, Paula Peare | 75 |
Investment Timing, Liquidity, and Agency Costs of Debt
Stefan Hirth, Marliese Uhrig-Homburg | 73 |
Sato Processes in Default Modeling
Thomas Kokholm, Elisa Nicolato | 72 |
On the Generalized Brownian Motion and its Applications in Finance
Esben Høg, Per Frederiksen, Daniel Schiemert | 68 |
GSE Funding Advantages and Mortgagor Benefits: Answers from Asset Pricing
Søren Willemann | 67 |
Rank papers for other periods
Top papers by Downloads last 3 months (2026-07 to 2026-09)
| Paper | Downloads |
Sato Processes in Default Modeling
Thomas Kokholm, Elisa Nicolato | 10 |
A Consistent Pricing Model for Index Options and Volatility Derivatives
Rama Cont, Thomas Kokholm | 10 |
Habit persistence: Explaining cross-sectional variation in returns and time-varying expected returns
Stig Vinther Møller | 9 |
Investment Timing, Liquidity, and Agency Costs of Debt
Stefan Hirth, Marliese Uhrig-Homburg | 9 |
On the Generalized Brownian Motion and its Applications in Finance
Esben Høg, Per Frederiksen, Daniel Schiemert | 9 |
Estimating US Monetary Policy Shocks Using a Factor-Augmented Vector Autoregression: An EM Algorithm Approach
Lasse Bork | 8 |
Dispersed Trading and the Prevention of Market Failure: The Case of the Copenhagen Stock Exchange
David C. Porter, Carsten Tanggaard, Daniel G. Weaver, Wei Yu | 8 |
Pricing the Option to Surrender in Incomplete Markets
Andrea Consiglio, Domenico De Giovanni | 8 |
Volatility and realized quadratic variation of differenced returns : A wavelet method approach
Esben Høg | 8 |
Time Charters with Purchase Options in Shipping: Valuation and Risk Management
Peter Løchte Jørgensen, Domenico De Giovanni | 7 |
Paying for Market Quality
Amber Anand, Carsten Tanggaard, Daniel G. Weaver | 7 |
The Forecast Performance of Competing Implied Volatility Measures: The Case of Individual Stocks
Leonidas Tsiaras | 7 |
Pricing of Traffic Light Options and other Correlation Derivatives
Thomas Kokholm | 7 |
Private benefits in corporate control transactions
Thomas Poulsen | 7 |
Traffic Light Options
Peter Løchte | 7 |
Investment decisions with benefits of control
Thomas Poulsen | 7 |
Rank papers for other periods
Top papers by Abstract Accesses all months (from 2005-09)
| Paper | Accesses |
A Consistent Pricing Model for Index Options and Volatility Derivatives
Rama Cont, Thomas Kokholm | 1548 |
The Fractional Ornstein-Uhlenbeck Process: Term Structure Theory and Application
Espen P. Høg, Per H. Frederiksen | 1531 |
Traffic Light Options
Peter Løchte | 1406 |
Debt and Taxes: Evidence from bank-financed unlisted firms
Jan Bartholdy, Cesário Mateus | 1392 |
Danish Mutual Fund Performance - Selectivity, Market Timing and Persistence.
Michael Christensen | 1386 |
Conducting event studies on a small stock exchange
Jan Bartholdy, Dennis Olson, Paula Peare | 1379 |
Realized Bond-Stock Correlation: Macroeconomic Announcement Effects
Charlotte Christiansen, Angelo Ranaldo | 1362 |
On the Generalized Brownian Motion and its Applications in Finance
Esben Høg, Per Frederiksen, Daniel Schiemert | 1223 |
Decomposing European bond and equity volatility
Charlotte Christiansen | 1208 |
Paying for Market Quality
Amber Anand, Carsten Tanggaard, Daniel G. Weaver | 1202 |
Rank papers for other periods
Top papers by Downloads all months (from 2005-09)
| Paper | Downloads |
Pricing the Option to Surrender in Incomplete Markets
Andrea Consiglio, Domenico De Giovanni | 329 |
The Fractional Ornstein-Uhlenbeck Process: Term Structure Theory and Application
Espen P. Høg, Per H. Frederiksen | 169 |
Lapse Rate Modeling: A Rational Expectation Approach
Domenico De Giovanni | 168 |
Danish Mutual Fund Performance - Selectivity, Market Timing and Persistence.
Michael Christensen | 168 |
Conducting event studies on a small stock exchange
Jan Bartholdy, Dennis Olson, Paula Peare | 145 |
Debt and Taxes: Evidence from bank-financed unlisted firms
Jan Bartholdy, Cesário Mateus | 145 |
A Consistent Pricing Model for Index Options and Volatility Derivatives
Rama Cont, Thomas Kokholm | 123 |
On the Generalized Brownian Motion and its Applications in Finance
Esben Høg, Per Frederiksen, Daniel Schiemert | 111 |
Decomposing European bond and equity volatility
Charlotte Christiansen | 110 |
Investment Timing, Liquidity, and Agency Costs of Debt
Stefan Hirth, Marliese Uhrig-Homburg | 108 |
Rank papers for other periods
Questions (including download problems) about the papers in this series should be directed to Helle Vinbaek Stenholt ()
Report other problems with accessing this service to Sune Karlsson ().
This page generated on 2026-10-01 05:46:56.