Scandinavian Working Papers in Business Administration
Finance Working Papers,
University of Aarhus, Aarhus School of Business, Department of Business Studies

Downloads from S-WoBA
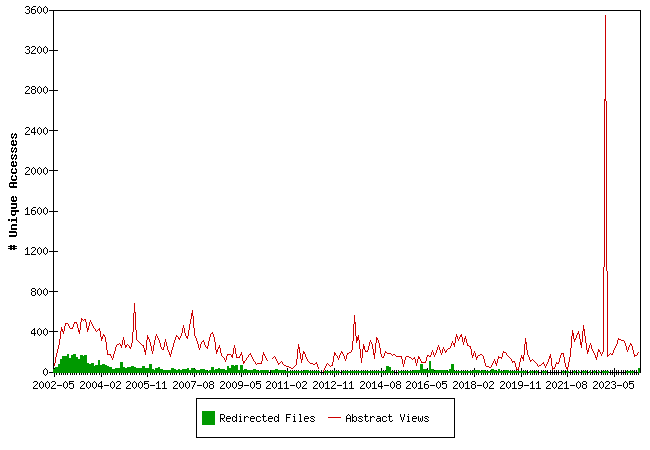
Fulltext files are files downloaded from the S-WoBA server, Redirected files are files downloaded from a server maintained by the publisher of a working paper series.

The statistics for 2010-06, 2012-04 (half month), 2012-05 and 2012-06 have unfortunately been lost. We regret this.

The raw data

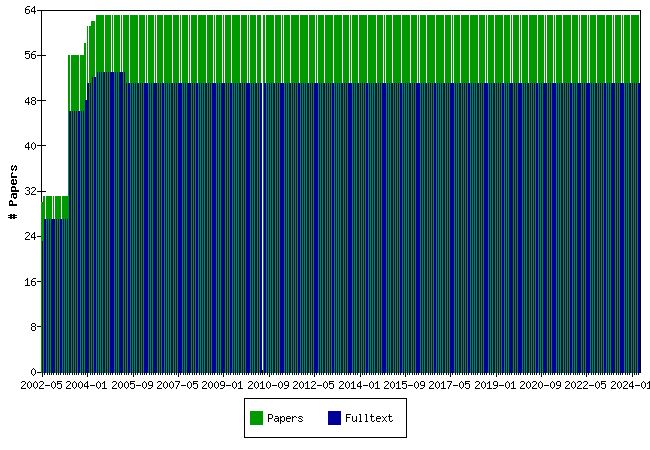
Papers at S-WoBA

The raw data

Top papers by Abstract Accesses last month (2026-10)

PaperAccesses
Mortgage Choice - The Danish Case
Mikkel Svenstrup
30
On the Suboptimality of Single-Factor Exercise Strategies for Bermudan Swaptions
Mikkel Svenstrup
29
Efficient Control Variates and Strategies for Bermudan Swaptions in a Libor Market Model
Malene Shin Jensen, Mikkel Svenstrup
26
Measuring Noise in the Permanent Income Hypothesis
Tom Engsted
26
Uncovered Interest Parity and Policy Behavior New Evidence.
Michael Christensen
23
Life Insurance Liabilities at Market Value.
Anders Grosen, Peter Løchte Jørgensen
23
Exchange Rate Dynamics in a General Equilibrium Model with Decreasing Returns to Labor.
Allan Bødskov Andersen
22
The Pros and Cons of Butterfly Barbells
Michael Christensen
22
Credit Spreads and the Term Structure of Interest Rates.
Charlotte Christiansen
22
Efficient Control Variates for Monte-Carlo Valuation of American Options
Nicki Søndergaard Rasmussen
22

Rank papers for other periods

Top papers by Downloads last month (2026-10)

PaperDownloads
Speculative bubbles in stock prices? Tests based on the price-dividend ratio.
Tom Engsted, Carsten Tanggaard
10
Volatility-Spillover E ffects in European Bond Markets
Charlotte Christiansen
9
Valuation of Path-Dependent Interest Rate Derivatives in a Finite Difference Setup
Mikkel Svenstrup
7
Misspecification versus bubbles in hyperinflation data: Comment.
Tom Engsted
5
Revisiting the shape of the yield curve: the effect of interest rate volatility.
Charlotte Christiansen, Jesper Lund
5
Mortgage Choice - The Danish Case
Mikkel Svenstrup
5
Evaluating the C-CAPM and the Equity Premium Puzzle at Short and Long Horizons: A Markovian Bootstrap Approach.
Tom Engsted, Enno Mammen, Carsten Tanggaard
5
Multivariate Term Structure Models with Level and Heteroskedasticity Effects
Charlotte Christiansen
4
Kernel Density Estimation of Actuarial Loss Functions.
Catalina Bolance, Montserrat Guillen, Jens Perch Nielsen
4
OBJECTIVES AND THEORETICAL FOUNDATIONS OF THE EUROPEAN COMMISSION’S 1999 ACTION PLAN CONCERNING THE FRAMEWORK FOR FINANCIAL MARKETS
Morten Balling
4
Further Evidence on Hedge Funds Performance.
Claus Bang Christiansen, Peter Brink Madsen, Michael Christensen
4
Boundary and Bias Correction in Kernel Hazard Estimation
Jens Perch Nielsen, Carsten Tanggaard
4
The Pros and Cons of Butterfly Barbells
Michael Christensen
4
Regime Switching in the Yield Curve
Charlotte Christiansen
4
The Educational Asset Market: A Finance Perspective on Human Capital Investment
Charlotte Christiansen, Helena Skyt Nielsen
4
Was the Honeymoon Effect Effective? An Analysis of the EMS Target Zone.
Allan Bødskov Andersen
4
Credit Spreads and the Term Structure of Interest Rates.
Charlotte Christiansen
4
Efficient Control Variates for Monte-Carlo Valuation of American Options
Nicki Søndergaard Rasmussen
4
Efficient Control Variates and Strategies for Bermudan Swaptions in a Libor Market Model
Malene Shin Jensen, Mikkel Svenstrup
4
Variable Bandwidth Kernel Hazard Estimators
Jens Perch Nielsen
4

Rank papers for other periods

Top papers by Abstract Accesses last 3 months (2026-08 to 2026-10)

PaperAccesses
Uncovered Interest Parity and Policy Behavior New Evidence.
Michael Christensen
79
Life Insurance Liabilities at Market Value.
Anders Grosen, Peter Løchte Jørgensen
73
Efficient Control Variates and Strategies for Bermudan Swaptions in a Libor Market Model
Malene Shin Jensen, Mikkel Svenstrup
72
Measuring Noise in the Permanent Income Hypothesis
Tom Engsted
69
MCMC Based Estimation of Term Structure Models.
Peter Mikkelsen
65
Boundary and Bias Correction in Kernel Hazard Estimation
Jens Perch Nielsen, Carsten Tanggaard
65
Mortgage Choice - The Danish Case
Mikkel Svenstrup
64
On the Suboptimality of Single-Factor Exercise Strategies for Bermudan Swaptions
Mikkel Svenstrup
64
A New Daily Dividend-adjusted Index for the Danish Stock Market, 1985-2002: Construction, Statistical Properties, and Return Predictability
Klaus Belter, Tom Engsted, Carsten Tanggaard
64
Efficient Control Variates for Monte-Carlo Valuation of American Options
Nicki Søndergaard Rasmussen
64

Rank papers for other periods

Top papers by Downloads last 3 months (2026-08 to 2026-10)

PaperDownloads
Volatility-Spillover E ffects in European Bond Markets
Charlotte Christiansen
18
Speculative bubbles in stock prices? Tests based on the price-dividend ratio.
Tom Engsted, Carsten Tanggaard
16
Was the Honeymoon Effect Effective? An Analysis of the EMS Target Zone.
Allan Bødskov Andersen
14
Multivariate Term Structure Models with Level and Heteroskedasticity Effects
Charlotte Christiansen
13
Variable Bandwidth Kernel Hazard Estimators
Jens Perch Nielsen
12
On Finite Dimensional HJM Representations.
Peter Mikkelsen
12
Further Evidence on Hedge Funds Performance.
Claus Bang Christiansen, Peter Brink Madsen, Michael Christensen
12
OBJECTIVES AND THEORETICAL FOUNDATIONS OF THE EUROPEAN COMMISSION’S 1999 ACTION PLAN CONCERNING THE FRAMEWORK FOR FINANCIAL MARKETS
Morten Balling
12
A Finite Difference Approach to the Valuation of Path Dependent Life Insurance Liabilities.
Anders Grosen, Bjarke Jensen, Peter Løchte Jørgensen
11
Mortgage Choice - The Danish Case
Mikkel Svenstrup
11
Evaluating the C-CAPM and the Equity Premium Puzzle at Short and Long Horizons: A Markovian Bootstrap Approach.
Tom Engsted, Enno Mammen, Carsten Tanggaard
11
The comovement of US and UK stock markets.
Tom Engsted, Carsten Tanggaard
11
Valuation of Path-Dependent Interest Rate Derivatives in a Finite Difference Setup
Mikkel Svenstrup
11
The Relation Between Asset Returns and Inflation at Short and Long Horizons.
Tom Engsted, Carsten Tanggaard
11

Rank papers for other periods

Top papers by Abstract Accesses all months (from 2002-05)

PaperAccesses
Credit Spreads and the Term Structure of Interest Rates.
Charlotte Christiansen
2341
Revisiting the shape of the yield curve: the effect of interest rate volatility.
Charlotte Christiansen, Jesper Lund
2266
Cross-Currency LIBOR Market Models.
Peter Mikkelsen
1957
MCMC Based Estimation of Term Structure Models.
Peter Mikkelsen
1908
A Finite Difference Approach to the Valuation of Path Dependent Life Insurance Liabilities.
Anders Grosen, Bjarke Jensen, Peter Løchte Jørgensen
1885
Implied Volatility of Interest Rate Options: An Empirical Investigation of the Market Model.
Charlotte Christiansen, Charlotte Strunk Hansen
1851
Real Supply Shocks and the Money Growth-Inflation Relationship.
Michael Christensen
1689
The Relation Between Asset Returns and Inflation at Short and Long Horizons.
Tom Engsted, Carsten Tanggaard
1654
Evaluating Danish Mutual Fund Performance
Michael Christensen
1634
Evaluating the C-CAPM and the Equity Premium Puzzle at Short and Long Horizons: A Markovian Bootstrap Approach.
Tom Engsted, Enno Mammen, Carsten Tanggaard
1632

Rank papers for other periods

Top papers by Downloads all months (from 2002-05)

PaperDownloads
Credit Spreads and the Term Structure of Interest Rates.
Charlotte Christiansen
420
Revisiting the shape of the yield curve: the effect of interest rate volatility.
Charlotte Christiansen, Jesper Lund
409
Cross-Currency LIBOR Market Models.
Peter Mikkelsen
395
Implied Volatility of Interest Rate Options: An Empirical Investigation of the Market Model.
Charlotte Christiansen, Charlotte Strunk Hansen
353
MCMC Based Estimation of Term Structure Models.
Peter Mikkelsen
282
Evaluating Danish Mutual Fund Performance
Michael Christensen
263
Evaluating the C-CAPM and the Equity Premium Puzzle at Short and Long Horizons: A Markovian Bootstrap Approach.
Tom Engsted, Enno Mammen, Carsten Tanggaard
237
The Relation Between Asset Returns and Inflation at Short and Long Horizons.
Tom Engsted, Carsten Tanggaard
231
Quantifying the "Peso Problem" Bias: A Switching Regime Approach.
Allan Bødskov Andersen
220
Further Evidence on Hedge Funds Performance.
Claus Bang Christiansen, Peter Brink Madsen, Michael Christensen
217

Rank papers for other periods

Questions (including download problems) about the papers in this series should be directed to Helle Vinbaek Stenholt ()
Report other problems with accessing this service to Sune Karlsson ().

This page generated on 2026-11-01 05:45:50.